
Barclays catalogue of errors

Imagine suddenly not being able to access your own money for no given reason even when you ask the bank, repeatedly, to resolve the problem. That’s what happened to Carole Railton, who is in her mid 70s. As a consumer expert I set about resolving the complaints.
Whilst breathless, homebound and waiting to have a pacemaker fitted, Barclays Bank suddenly prevented Carole from accessing her bank account, without any explanation. They told her (incorrectly) that they were allowed 8 weeks to resolve the issue. In fact, a customer has 8 weeks from starting a complaint with a financial institution to take the matter to the Financial Ombudsman, or the customer can ask for a deadlock letter to take the matter earlier. A financial institution should never be working to an 8 week deadline to resolve an issue.
The Consumer Duty
The Consumer Duty requires financial firms to
consider the needs, characteristics and objectives of their customers – including those with characteristics of vulnerability – and how they behave, at every stage of the customer journey. As well as acting to deliver good customer outcomes, firms will need to understand and evidence whether those outcomes are being met.”
Barclays breached this duty numerous times.
The Consumer Duty came into force on the 31st July 2023 and the complaint started on the 19th July 2023. When I asked the Financial Conduct Authority (FCA) about existing complaints started before this date it made it clear to me that “We expect all firms in their current dealings with consumers to be applying the Consumer Duty regardless of when any poor service may have started.”
Barclays offer of support
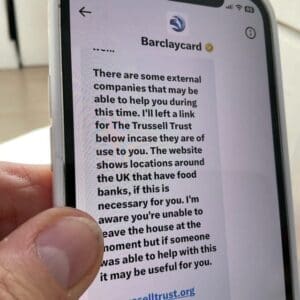
Carole had to borrow money to get deliveries for food whilst Barclays told her to access a food bank. In addition to this being highly inappropriate advice, particularly when Barclays was at fault, it shows a complete lack of understanding or regard for how referral works. Banks, unsurprisingly, cannot refer people to food banks!
Trying to get Barclays to resolve the issue
After three weeks without money, I got involved. The bank told Carole she could have a video call. The link for this call never arrived, nor did an explanation or apology.
When she eventually got the call (that I had insisted should be recorded so she could use it to send to the Financial Ombudsman) the bank told her that it would be recorded by Barclays and she would have to make a Subject Access Request to get a copy!
Barclays told Carole to visit a bank. Two issues with this: Firstly she had informed them that she was not able to travel. Secondly, she later found out that that bank branch didn’t exist! It had closed down!
Other issues included being told someone would come to her house, but they didn’t. Ridiculous exchanges on Twitter (as it was then) included social media staff suggesting the food bank and receiving calls from people at Barclays who had no knowledge of the history of the situation.
On another call that did not provide a resolution, Carole explained her health. Barclays gave her links to NHS mental health resources! Talk about not taking any responsibility! The irony is that in every correspondence Barclays thanked Carole for her patience, which is such a pointless and stupid thing that so many businesses say when (not) dealing with a complaint. If a company is dealing with a complaint badly then customers can only wait for a solution, patiently or not.
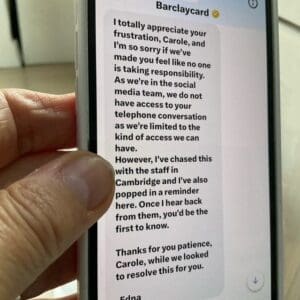

Barclays refused to deal with me, as a third party, despite Carole’s specific permission and request for them to do so. They then told me that the account had had some fraudulent activity associated with it but did not tell Carole! I still carried on trying to resolve the shocking service issue.
When we thought the matter was finally resolved, I requested and expected Barclays to immediately deliver the card by courier. Instead they asked her to pay for the card to be expedited to be able to reactivate her account, meaning that it would arrive the day she was due for her operation! It arrived the day she was in hospital.
Barclays told me that they had sent the card to Carole. However, she was in hospital! We had already told them this but they ignored it.
I created and sent Barclays a spreadsheet that detailed every time a call/tweet/email letter was sent or received. There were over 40 touch points where Barclays had been in communication with Carole or myself and each one of them had failed to achieve any resolution and many of them promised action that did not happen.
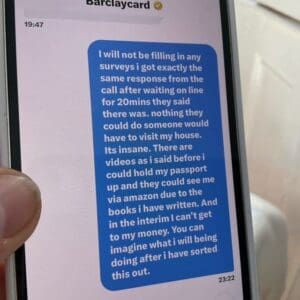
The second time Carole was asked to fill out a feedback form when nothing had been resolved and before I even got involved!
Barclays poor customer service contributes to Carole being readmitted to hospital
The stress caused, by Barclays appalling service, contributed to Carole having to seek medical help, even before her scheduled heart operation. She was taken into hospital.
Barclays breach of the Consumer Duty
I repeatedly informed Barclays of its breaches of the Consumer Duty:
- “helpful and accessible customer support, so it’s as easy to sort out a problem”
- “firms to consider if you’re in a vulnerable situation when dealing with you.
- FCA Conduct Rules breach
- “Rule 1: You must act with integrity.”
- Rule 2: You must act with due skill, care and diligence.”
- Rule 4: You must pay due regard to the interests of customers and treat them fairly and
- The Consumer Rights Act 2015 states that companies must provide services with reasonable care and skill. Barclays clearly breached the Act in this case.
Barclays finally give Carole access to her account
Eventually I got the account working, an apology from Barclays and £500 compensation for Carole. But many of the issues were still not addressed and Barclays has ignored requests for an updated statement to reflect the continued errors and poor service Carole has received.
Despite numerous requests for a statement that reflected over 40 touch points of failure, (and numerous other Direct Messages in Twitter that were useless), Barclays would only supply this statement.
Unfortunately, on this occasion we failed to provide the high level of service that our customers can rightly expect to receive, for which we sincerely apologise. We’re very sorry for the distress and inconvenience caused to the customer whilst they were trying to access their funds, after there were delays in removing a block which had been applied to protect their account. All blocks have now been removed, and we have offered the customer a gesture of goodwill for the stress and inconvenience caused.”
New Barclays complaint
Fast forward four months: Carole put the proceeds of her house sale into the account. Barclays closed the account without Carole’s knowledge and without her permission. She went into the branch to be told it was all fine but it wasn’t because the card still did not work.
When Carole wrote to the CEO the person from the complaints department told her that he had 8 weeks to resolve the issue. (It would appear that Barclays’ staff are told to say this!) Barclays told Carole that she can only keep the money in the account for six months. Barclays told Carole that she would be charged £25 for every £25,000 she moves out of the account. They said if she did it online, she could do it for free. This is yet another breach of the Consumer Duty, not considering vulnerabilities, Carole’s age and that she is dyslexic. Discriminating against someone for not being able to use online services is a clear breach of the Consumer Duty.
Carole is moving her money to Nationwide and being paid £200 to do so. Barclays loses a customer due wholly to poor customer service and breaches of the Consumer Duty.
FCA Review into bank access
In September 2023 The Financial Conduct Authority (FCA) launched a review UK Payment Accounts: access and closures about the scale of account closures and access to financial services. The report uncovered a number of areas that require follow up to confirm its understanding, as well as to address the causes and impact of the concerns.
The review stated that by far the most common reasons providers gave for declining, suspending or terminating an account were because it was inactive/dormant or because there were concerns about financial crime.
One of the actions the FCA has instructed financial institutions to undertake is:
The Duty also requires firms to define, monitor, evidence and stand behind the outcomes their customers are getting. This monitoring must enable firms to identify where customers are getting poor outcomes, and where this is the case firms must take appropriate action to rectify the situation.”
The FCA engages with consumer groups and organisations which give the FCA information, sharing their members’ concerns on these issues. It puts these together with the insights from its own data collection to understand experiences and the impact of account declines, terminations and suspensions. The FCA requested the full log of the issues and breaches from me and this has been sent.
The Financial Ombudsman statistics on frozen or suspended accounts
The table below is information regarding how many complaints the FOS received regarding frozen or suspended accounts was requested by me and is not published information.
| Financial year | New complaints | Number of resolved complaints | Uphold rate |
| April – December 2023 | 1,632 | 2,081 | 39% |
| 1 April 2021– 31 March 2022 | 2,349 | 2,483 | 30% |
Barclays topped the FOS half-yearly complaints data for the first part of 2023.
13/12/23 Barclays has been approached for comment. As of 19 December it has refused to do so and the mater is being progressed with the Financial Ombudsman.
For further information on this case, the spreadsheet and pictures please contact me.
Help with financial complaints
How to complain about financial institutions various posts covering ways to complain about different financial firms.
To ensure that you know your rights and how to use them take a look at How to Complain: The Essential Consumer Guide to Getting Refunds, Redress and Results, as one reviewer says you’ll get more than your money back the first time you use it!

101 Habits of an Effective complainer designed to improve the way you look at and make complaints. Each page gives you a complaining habit to consider and an example of how and why it empowers you to become more effective in getting the results you want.

Purchase downloadable templates to gain redress to get refunds and redress just fill in your personal situation info